Trust
Crypto-Backed Lending 101: Every Term You Need to Know

October 6, 2026
Read more


In 2022, customers of Celsius and Voyager logged in to find their accounts frozen. They'd handed over their crypto expecting to get it back. Many recovered only part of what they were owed, years later.
Those collapses gave crypto lending a bad name. They also taught a lesson worth holding onto: borrowing against your crypto can be one of the smartest financial moves you make, as long as you know exactly what you're signing and who you're signing with.
The basic deal is simple. You pledge crypto as collateral, take a loan in cash, and get your assets back when you repay. You skip the sale, keep your position, and get liquidity on your own timeline. It's how many founders and high-net-worth holders fund their next move without leaving the market.
Done badly, it's how people lose far more than they planned. This guide covers everything in between, one term at a time.
This is the whole point. Selling your crypto can trigger a taxable event and takes you out of the market. Borrowing against it gives you liquidity while you keep your position. Talk to your accountant about how this applies to you, since tax treatment depends on your situation.
Be clear with yourself about why you're borrowing. Funding a business, covering a tax bill, or bridging to a property purchase are all common reasons. Using borrowed money to buy more crypto adds leverage on top of leverage, so go in with eyes open.
Many borrowers aren't buying a car or a cottage. They're funding a business: bridging a cash gap, buying equipment, or closing a deal fast. Crypto-backed loans can move faster than traditional bank credit because approval is anchored to the collateral.
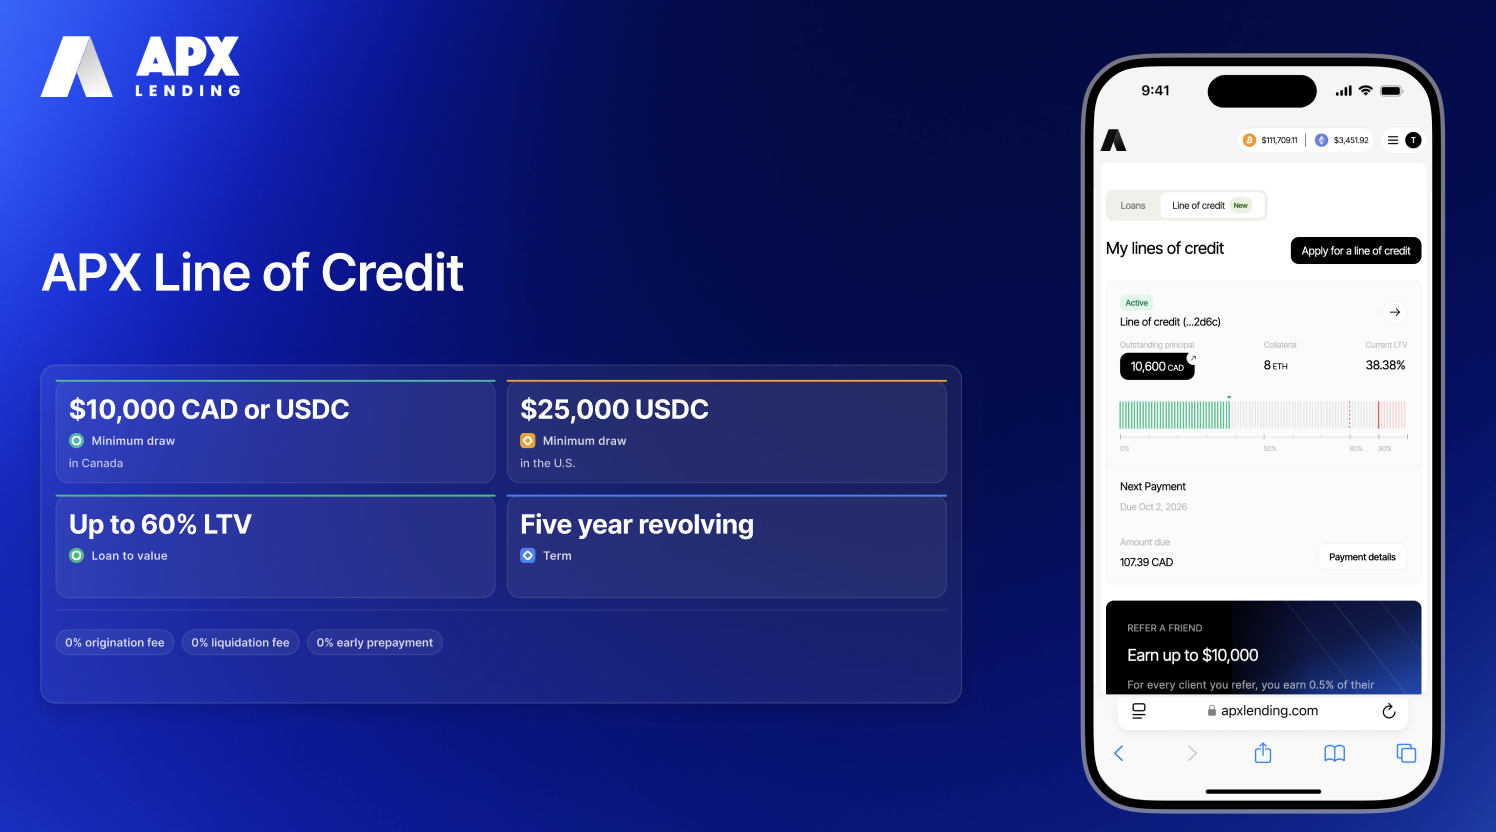
A standard loan gives you all the cash up front, and you pay interest on the full amount from day one. A line of credit works differently. Your collateral sets your credit limit, you draw cash when you need it, and you pay interest only on what you've drawn. With most lines of credit, repaying frees that room up to use again.
An LOC suits borrowers whose cash needs come in waves, like entrepreneurs managing payroll, inventory, or a deal that might close next month or next quarter. It's the reason we built the APX Credit Line.
Origination is the process of setting up your loan: application, verification, collateral transfer, and funding. Some lenders charge an origination fee for this. Ask how long it takes from application to cash in your account.
How long is the loan, and what happens at the end? Can you repay early without penalty? Can you renew or roll it over? Match the term to what you're using the money for.
Know how you'll repay before you borrow. Will it come from business revenue, a property sale, or selling some crypto later at a better price? A loan with a clear way out is a tool. A loan without one is a bet.
LTV is the most important number in your loan. It's your loan balance divided by the current value of your collateral.
Say you pledge $200,000 of crypto and borrow $100,000. Your LTV is 50%. If your collateral drops to $150,000, your LTV climbs to about 67%. The lower you start, the more room you have to absorb a market drop.
Crypto moves fast, and sometimes overnight. That's why crypto loans start at lower LTVs than a mortgage would. A cushion that feels overly cautious in a calm week is exactly what protects you in a rough one.
When you borrow against crypto, you keep your upside if prices rise. You also keep your downside. Borrowing doesn't hedge you. It lets you stay in the market while unlocking cash, so plan for both directions.
When your LTV rises past a set threshold, the lender asks you to bring it back down, either by adding collateral or paying down part of the loan. Find out what the thresholds are, how you'll be notified, and how long you have to respond.
If your LTV hits the liquidation threshold and you haven't topped up, the lender sells collateral to protect the loan. The question is how much. Some lenders sell everything. Others sell only what's needed.
APX follows what we call the 90/85 Standard. If your LTV reaches 90%, we sell only enough collateral to bring your account back to 85%. You keep the rest of your position and your loan stays open. Some lenders also charge several percent on top of a liquidation. APX charges 0%, because a bad market day is costly enough already.
Before you borrow, run the numbers. What happens to your LTV if your collateral drops 20%? 40%? Do you have cash or extra crypto on hand to top up? Borrowing comfortably means knowing your margin call price before the market finds it for you.
With a non-recourse loan, the lender's only claim is on the collateral you pledged. With a recourse loan, they can come after your other assets if the collateral falls short. Read this part of the agreement carefully.
The annual percentage rate is what your loan really costs per year, including interest and any fees rolled in. Two loans with the same headline interest rate can have very different APRs. Always compare APR to APR.
Interest can be fixed or variable, paid monthly or accrued to the end of the term. Some lenders let interest accrue against your collateral, which keeps your cash flow free but quietly raises your LTV over time. Know which one you're signing up for.
Origination fees, early repayment fees, withdrawal fees, liquidation fees. Ask for the full list in writing. A low rate with a stack of fees is not a cheap loan.
Regulation is what separates a lender from a platform that just hasn't failed yet. In Canada, crypto lending sits under the oversight of provincial securities regulators that make up the Canadian Securities Administrators (CSA). APX is CSA-regulated, which means real rules on custody, disclosure, and how client assets are handled.
Where is your lender regulated, and where would a dispute be settled? A lender operating under Canadian securities regulators plays by very different rules than an offshore platform with no oversight. Jurisdiction decides what protections you actually have if something goes wrong.
Who holds your collateral while the loan is open? This is the single most important question in crypto lending. Look for lenders that use institutional-grade, segregated custody. At APX, client collateral is held in cold storage with BitGo, with Fireblocks as part of our custody stack.
Hypothecation just means pledging an asset as collateral without giving up ownership. Rehypothecation is when the lender takes your collateral and lends it out or uses it elsewhere to earn more. That's where many of the 2022 lender collapses came from. Ask any lender directly whether your collateral is rehypothecated, and get the answer in writing.
Borrowing against your crypto and earning yield on your crypto are two different things, and they carry very different risks. Many of the platforms that collapsed in 2022 paid depositors high yields by lending their assets out. When you're borrowing, your collateral should be sitting still, held safely, and waiting for you.
Know Your Customer checks verify who you are. Reputable lenders require them. If a platform will lend you six figures with no identity checks, treat that as a warning sign rather than a convenience.
Crypto-backed loans aren't only offered by dedicated lenders anymore. Exchanges and fintechs can offer them to their own customers using another company's lending infrastructure under their own brand. APX powers this through our Lending as a Service (LaaS) platform, including our partnership with Netcoins. If your exchange offers loans, it's worth asking whose infrastructure sits behind them.
If a lender hesitates on any of these, keep looking.
Crypto-backed lending lets you put your digital assets to work without letting them go. The best loans come from lenders who are regulated, transparent about custody, clear on their thresholds, and fair when markets get rough.
If you're thinking about borrowing against your crypto, we'd be glad to walk you through how it works at APX. Talk to our team and we'll help you figure out whether a loan or a credit line fits what you're planning.
This article is for informational and educational purposes only and does not constitute legal, financial, investment, or tax advice. APX Lending does not provide investment or tax recommendations. Borrowers should consult qualified professionals and conduct their own due diligence before entering into any crypto-backed lending arrangement.